
 See My Latest Article on HelloNation
What does it mean to amend a tax return?
Amending a tax return means filing a corrected version after the original return has already been submitted. An amendment may be needed when income, filing status, deductions, credits, dependents, or tax liability was reported incorrectly.
For a resident of Franklin, IN, a correction may involve both the federal return and the Indiana return. Federal and state filings are separate, so fixing one does not automatically update the other.
An amended return generally changes information that affects the tax calculation. It is not simply a replacement copy of the original return.
Which mistakes require an amended return?
An amended return is commonly appropriate when:
- A W-2, 1099, or other income document was left off the return
- Income was reported in the wrong amount
- The filing status was incorrect
- A dependent was omitted or incorrectly claimed
- A deduction or tax credit was missed
- A deduction or credit was claimed incorrectly
- A change to adjusted gross income affects another part of the return
- The IRS or Indiana Department of Revenue adjusted information and the taxpayer needs to report a related change
For example, a household may receive a corrected 1099 after filing. If the corrected amount changes taxable income, deductions, or credits, the return may need to be amended.
An amendment may not be necessary for a simple math or typing error if the tax agency corrects it during processing. A missing attachment also may not require an amendment if the agency requests the document separately. However, missing income or a change that affects tax generally requires more than sending in an attachment.
What federal form is used to correct a return?
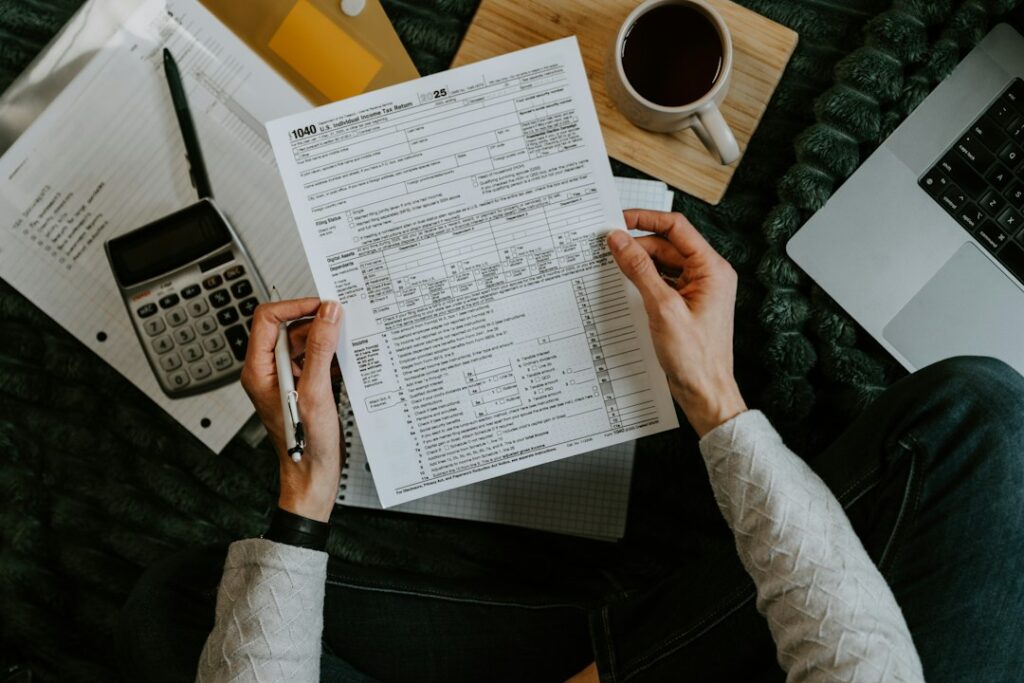
Most individuals use Form 1040-X, Amended U.S. Individual Income Tax Return. A separate Form 1040-X is generally filed for each tax year being corrected.
The form compares three figures:
- The amounts originally reported or previously adjusted
- The net change being made
- The corrected amounts
The amendment must also explain why the change is being made. Supporting schedules and forms should be included when they relate to the correction. For instance, a newly reported W-2 or corrected deduction may require an updated schedule or a copy of the supporting document.
Federal amended returns may be filed electronically in many situations. Paper filing remains available, particularly when electronic filing is not supported for the specific correction or tax year.
How does an Indiana resident amend a state return?
Indiana generally requires a state amendment when a federal amendment changes information used on the Indiana return. The state filing process depends on the tax year.
For tax years 2021 and later, an amended Indiana individual return is generally filed by selecting the “Amended” option on the applicable IT-40 form. For tax years 2020 and earlier, taxpayers who already filed an Indiana return generally use Form IT-40X.
The corrected Indiana return should include the forms and schedules affected by the change. If an amended federal return was filed but no original Indiana return was filed for that year, the Indiana filing may need to be submitted as an original return using the corrected figures rather than as an amended return.
State and federal amendments should be prepared consistently. A change to federal adjusted gross income, for example, may affect Indiana income, deductions, credits, or county tax calculations.
Should the federal or state amendment be filed first?
It is usually practical to complete the federal correction before finalizing the state amendment when the state return depends on federal figures. The corrected federal amounts can then be used to prepare the Indiana filing.
The original return should generally be processed before an amendment is submitted. Filing an amendment too soon can create confusion if the first return is still being matched, reviewed, or adjusted.
If the amendment results in additional tax, paying the amount due as soon as reasonably possible can reduce the buildup of interest and penalties. Filing the amended return does not always stop interest from accumulating on an unpaid balance.
How long is there to amend a return?
The deadline depends on whether the amendment claims a refund, reports additional tax, or involves a special rule.
For a federal refund claim, the general deadline is the later of:
- Three years after the original return was filed
- Two years after the tax was paid
If a return was filed before the regular filing deadline, the three-year period generally begins with the original due date rather than the early filing date.
Indiana generally allows an amended return within three years after the original due date or the date the tax was paid, whichever is later. Special circumstances can create different deadlines, so an older return should not be assumed to be outside the filing period without checking the rules for that specific year.
An amendment that increases tax should still be filed promptly even if the refund deadline has passed. Waiting can increase interest and penalties.
What documents should be gathered before starting?
Preparation is easier when the original filing and all related records are available. Useful documents include:

- A copy of the original federal and Indiana returns
- Any previously filed amendments
- W-2s, 1099s, corrected income statements, and other tax documents
- Receipts or records supporting deductions
- Forms supporting education, dependent, retirement, or other credits
- Notices received from the IRS or Indiana Department of Revenue
- Records of tax payments and refunds already received
The amendment should use the original figures as filed or as later adjusted by the tax agency. It should not automatically use a previously prepared draft or an amount from a tax document unless that amount is the correct figure for the return being changed.
What happens if the amendment shows a refund or more tax owed?
If the corrected return shows a refund, the refund is generally issued separately from any refund on the original return. The original return should be allowed time to finish processing before relying on the amended calculation.
If more tax is owed, the balance should be paid as soon as possible. An amended return does not erase the original due date, so interest or penalties may apply depending on the circumstances.
A larger refund is not automatically correct. Changes to income can affect several connected items, including tax credits, itemized deductions, taxable Social Security benefits, education benefits, and other income-based calculations. Every affected schedule should be reviewed rather than changing only the line where the original mistake appeared.
How can the status of an amended return be checked?
Federal amended-return status is generally available through the IRS amended-return tracking system about three weeks after submission. Processing often takes considerably longer than an original electronic return and may take several weeks or more.
State processing has its own review process and timing. Keep a copy of the complete amended filing, proof of electronic submission or mailing, payment records, and any confirmation numbers.
Residents who receive a notice after filing should compare the notice with the amended return and respond by the deadline shown. A notice does not necessarily mean the amendment was rejected; it may request clarification, documentation, or payment.
Common mistakes to avoid
Several problems can delay an amendment:
- Filing only the federal amendment when the Indiana return also changed
- Sending a state amendment with figures that do not match the corrected federal return
- Forgetting to include a revised schedule
- Reporting a refund already received as a new estimated payment
- Failing to explain the reason for the change
- Filing before the original return has finished processing
- Assuming a second amendment will automatically replace the first one
- Waiting to pay additional tax while interest continues to accrue
A careful amendment starts with identifying the exact error, recalculating every affected item, and checking the filing deadline for the particular tax year. For households managing seasonal employment, changing family circumstances, retirement distributions, or multiple income forms, keeping organized records throughout the year can make a later correction much simpler.